
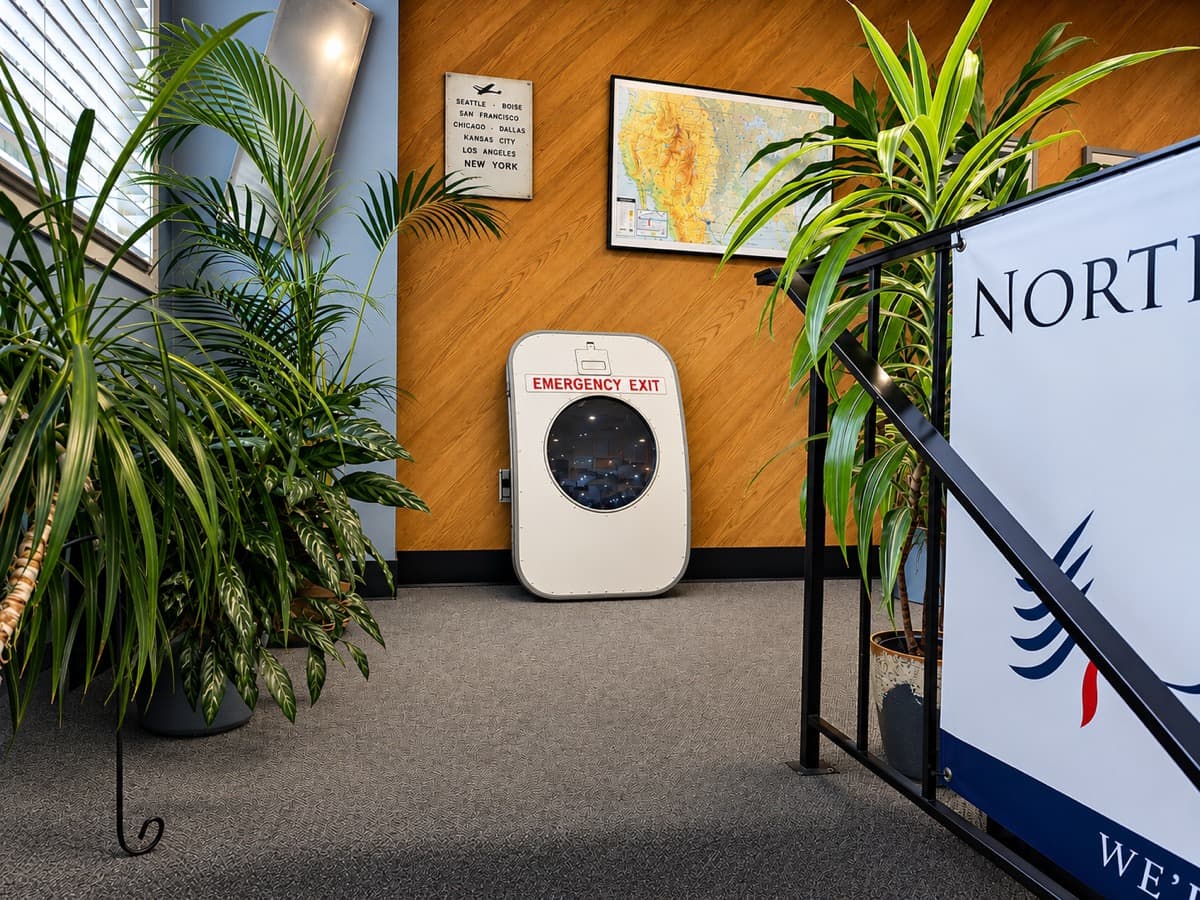
As you come up the staircase into the reception area of our aviation insurance agency, you’ll find an aircraft emergency exit door from a commuter turboprop. I often invite visitors to pick it up. Most are surprised by how heavy and cumbersome it is.
The door has a fantastic story I was proud to be part of, but that’s a story for another day. I placed it there to make a point. Anyone who has occupied an emergency exit row has accepted certain responsibilities, whether they’ve given those responsibilities much thought or not. Picking up that door makes those obligations suddenly more tangible.
Being the named insured on an aviation insurance policy isn’t very different. You accept responsibilities when you purchase the policy, and those responsibilities don’t disappear simply because something has gone wrong.
My office overlooks the end of a runway at one of Oregon’s busy general aviation airports. For 25 years I’ve witnessed nearly every kind of incident and accident imaginable, right outside my window. One day I watched a large twin-engine airplane skid gear-up down the runway and slide to a stop. The pilot climbed out, pulled out his cell phone and made a call. My telephone rang. I answered, looked out the window and waved at him. He waved back and asked, “Now what?”
Keep in mind, this is a tower-controlled airport. Airport management, emergency responders, the FAA, and pretty much everyone else were already on their way to help him out. But I must admit, I felt a little special being his first phone call.
Not every call comes from a pilot standing safely beside an airplane on the runway. Sometimes the aircraft is stranded somewhere remote and the pilot is stranded with it. The pilot needs rescue, the airplane needs recovery, and neither operation begins with an insurance adjuster. I won’t explore first aid, survival techniques, or emergency preparedness here. There’s an enormous amount of excellent information already available on those subjects. Instead, I want to address a few important steps in understanding when and how insurance becomes part of the process.
The immediate priorities are straightforward. Preserve life, starting with your own. Call first responders when necessary and take reasonable steps to prevent additional property damage without compromising safety. Then make the required notifications, including your insurance broker or carrier and authorities, such as the NTSB or FAA.
Virtually every aviation insurance policy contains a requirement to report an occurrence promptly. The language varies from “immediately” to “as soon as practicable,” but the obligation is essentially the same.
And here’s something many insureds misunderstand: You don’t have to know whether you have a claim before reporting an occurrence.
An occurrence and a claim are not necessarily the same thing. You may not know the full extent of the damage, who is responsible, or whether insurance coverage will ultimately be needed. Reporting gives the insurance company an opportunity to open a file, gather information, and determine what may be needed next. Sometimes the file simply remains open while everyone waits for additional information or even your decision about whether to pursue a claim. Not every occurrence results in a request for payment.
Even after the immediate emergency has concluded, you might assume it’s time for the insurance company to take over. Not necessarily. Depending on the circumstances, authorities may retain control of the aircraft, property, or site of the occurrence while investigating. Until the property or site is released by the appropriate authorities, the insurer may have limited ability to inspect the aircraft, recover it, or authorize repairs.
And consider that pilot stranded somewhere remote. A policy may provide certain search-and-rescue or recovery benefits, subject to its terms and limits. But the insurance company isn’t going to dispatch a search and rescue operation to come get you. That’s a rescue operation, not an insurance claim service. There’s a difference between arranging emergency assistance and having insurance available to pay eligible expenses afterward.
Another common misunderstanding is that once an insurance company becomes involved, it takes control of the loss. Generally, it doesn’t. The insurance company doesn’t ordinarily select the repair facility, decide exactly how an aircraft should be repaired, or manage the repair process. Those decisions involve the aircraft owner, maintenance professionals, and applicable regulatory requirements.
What the insurance company does determine is what it is obligated to pay under the terms of the insurance contract. You may prefer a particular repair facility, replacement component, or method of repair, but that doesn’t automatically obligate the insurer to pay whatever it costs.
Likewise, an adjuster’s agreement to a repair estimate doesn’t make the adjuster responsible for the quality of the work. Insurance provides the financial resources to manage a covered loss. It doesn’t relieve the aircraft owner of responsibility for managing it.
There is one significant exception to this division of responsibilities: Legal defense. When an occurrence results in a liability claim or lawsuit covered by a policy’s duty-to-defend provisions, responsibility for providing a legal defense generally shifts to the insurance company.
The matter is assigned to legal counsel, either through the insurer’s legal department or outside attorneys retained to represent the insured. Unlike selecting an aircraft repair facility, the insured ordinarily doesn’t control the selection of defense counsel or the expenses associated with conducting that defense. Legal bills can be enormous, even when the insured hasn’t done anything wrong.
And here’s something that doesn’t always sit well with pilots and aircraft owners. Liability claims are sometimes settled for financial reasons rather than because anyone has established fault. Lawsuits are expensive to defend, and those costs can multiply quickly when additional people are involved, sometimes because of contractual agreements made long before the loss.
Depending on the policy’s terms, the insurer may conclude that settling is the most practical solution. That can be a bitter pill to swallow when you’ve done nothing wrong. It’s also why you need to cooperate and avoid making statements or commitments that could compromise the defense.
Aviation insurance policies are manuscript contracts, which means they are custom-written for a specific policyholder, and the circumstances surrounding every loss are different. No single article can explain exactly how every insurance company will respond to every occurrence. Policies can provide an extraordinary range of assistance, from repairing or replacing an aircraft to responding to liability claims and other covered expenses.
But regardless of which coverage may ultimately respond, there are contractual conditions that must be satisfied. Reporting an occurrence is not the end of your responsibilities. It’s the beginning of a process that requires your continued cooperation.
That emergency exit door in our reception area serves as a reminder that accepting responsibility and understanding it are two very different things. The passenger seated beside it may never need to open it, but that doesn’t diminish the responsibility they’ve accepted.
Insurance can provide financial resources to recover from a loss. It doesn’t relieve you of the responsibility for managing what happens next. And when the unexpected happens, understanding what remains on your shoulders may be just as important as knowing what’s covered by your policy.
Leave a Reply